What Happens When a Trucking Company's Insurance Isn't Enough?
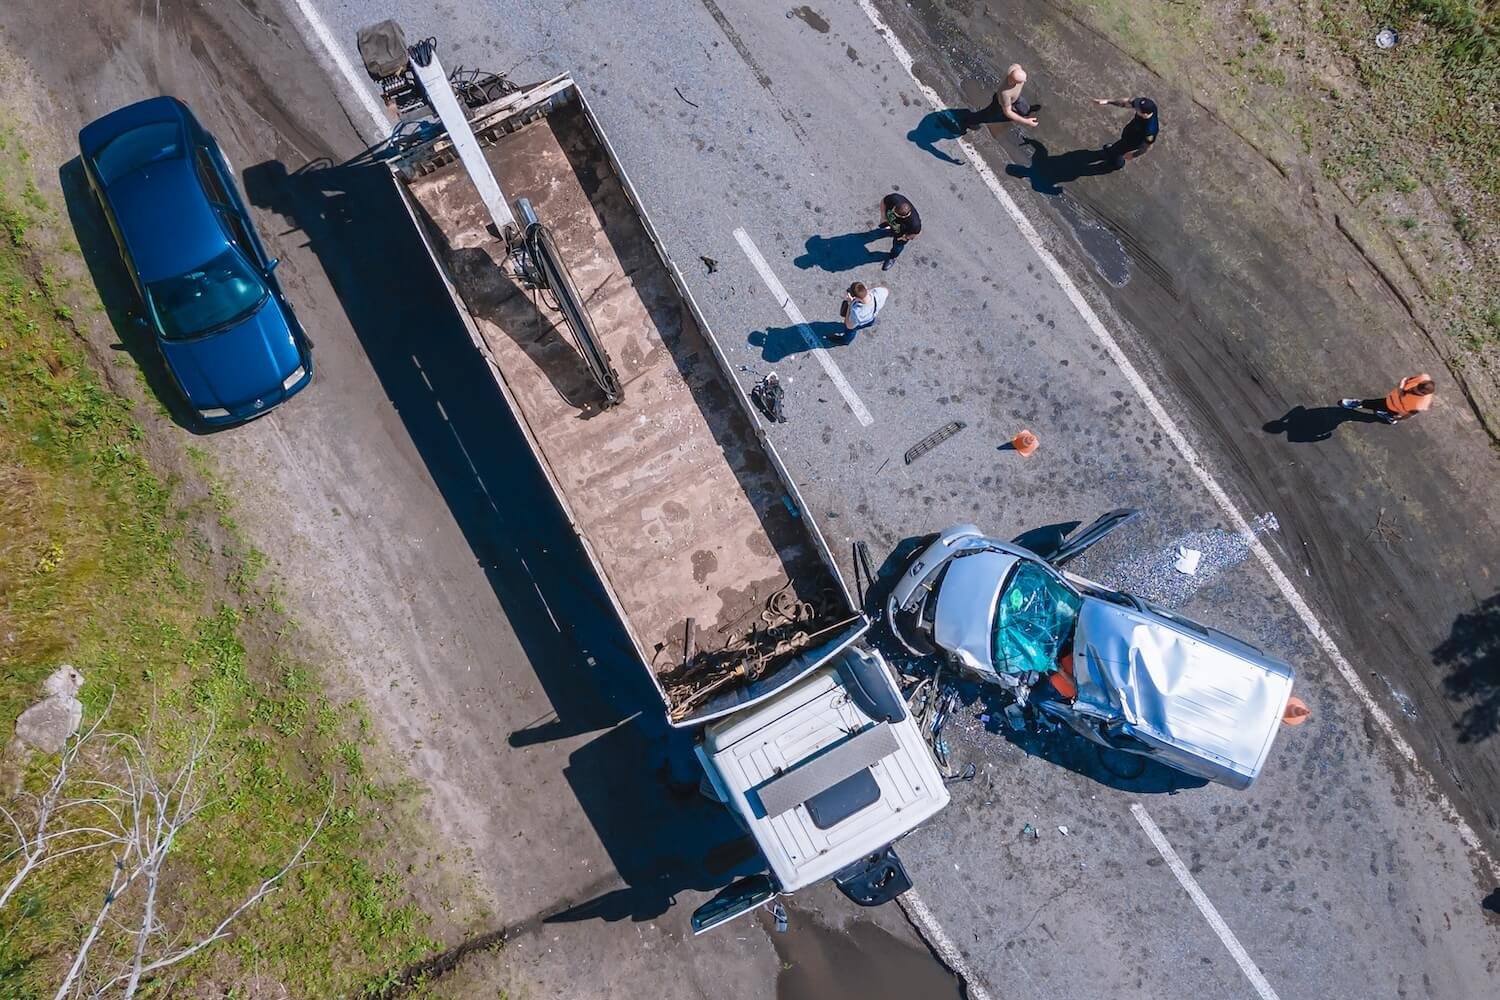
A serious truck accident can change a family’s financial future in seconds. Medical bills accumulate. Income disappears. Rehabilitation continues for months or years. In the most devastating cases, an injured person may need lifelong care.
Then comes another problem: The trucking company’s insurance may not be enough to cover the damage.
Many people assume that once an insurance company reaches its policy limit, there’s nothing more they can do. But the amount of insurance available and the amount of compensation someone may legally recover are not necessarily the same.
In Washington, a commercial truck accident investigation may uncover additional insurance policies, other legally responsible companies, and sources of compensation that aren’t immediately apparent.
Understanding those possibilities can make a significant difference, especially when an accident causes permanent disability, catastrophic injuries, or wrongful death.
What Happens When a Truck Accident Claim Exceeds the Insurance Policy Limits?
When a truck accident claim exceeds the available insurance limits, the injured person may still have legal options. Additional coverage, other responsible parties, or the assets of a liable defendant may provide possible sources of recovery. Whether those options exist depends on the facts, applicable law, and available insurance.
Consider a hypothetical example.
A commercial truck causes a collision that leaves someone with a spinal cord injury. Between hospitalization, rehabilitation, lost income, future medical treatment, and other damages, their legally supportable losses total $2.5 million.
The trucking company’s primary liability policy provides $1 million.
That leaves a potential $1.5 million gap between the damages and the insurance coverage.
The insurance company generally isn’t required to pay beyond its contractual limits simply because the injuries are severe. But the investigation shouldn’t automatically end at that policy.
It should answer three questions:
Is additional insurance available?
Did another company or individual contribute to the accident?
Are there other legally recoverable sources of compensation?
Those questions are particularly important in commercial trucking cases, where multiple businesses may participate in a single shipment.
How Much Insurance Are Commercial Trucking Companies Required to Carry?
Commercial trucking insurance requirements depend on the type of carrier, the vehicle, its operations, and the cargo being transported.
Under 49 CFR § 387.9, many interstate for-hire carriers transporting nonhazardous property in vehicles weighing at least 10,001 pounds must maintain at least $750,000 in public liability financial responsibility.
Certain hazardous material operations require minimum limits of $1 million or $5 million.
These are federal minimums for specified operations, not universal insurance limits for every commercial truck in Washington. State requirements and other rules may also apply.
Some trucking companies purchase substantially more coverage. Others maintain only the amount required for their operations.
The distinction matters because serious injuries can generate damages that exceed even a seven-figure policy.
A $750,000 or $1 million policy may sound substantial. But when someone requires long-term medical treatment, loses decades of earning capacity, or needs ongoing personal assistance, the financial consequences can extend far beyond the initial hospital bills.
Four Potential Sources of Compensation Beyond the Primary Trucking Policy
Finding additional compensation requires more than asking the insurance company to increase its offer. It requires identifying the policies, businesses, and legal responsibilities involved in the collision.
1. Excess or Umbrella Insurance Coverage
The first question is whether the trucking company maintains additional insurance.
Commercial carriers sometimes purchase excess liability policies that provide coverage above their primary policy limits. Some businesses also have umbrella policies that may apply, depending on their terms.
For example, a trucking company might carry $1 million in primary liability coverage and a separate excess policy providing additional protection.
The total available coverage could be substantially higher than the amount initially identified.
However, excess insurance doesn’t necessarily apply to every claim. Coverage can depend on exclusions, policy conditions, the insured businesses, and whether the underlying limits have been exhausted.
A thorough review of the actual insurance policies is necessary before determining how much coverage may be available.
2. Other Companies That May Share Legal Responsibility
A commercial truck accident may involve more businesses than the trucking company whose name appears on the vehicle.
The driver may work for a motor carrier operating leased equipment. A separate company may own the trailer. Another business may have loaded the cargo, maintained the truck, or arranged the shipment.
Depending on the circumstances, potentially responsible parties could include the motor carrier, an equipment maintenance contractor, a negligent cargo-loading company, or a freight broker involved in selecting an unsafe carrier.
The important distinction is that participation in a shipment doesn’t automatically create legal liability.
There must be a factual and legal basis for holding each party responsible.
Washington’s RCW 4.22.070 addresses how fault is allocated among multiple responsible parties, including circumstances in which joint and several liability may apply.
Identifying another responsible company may also reveal a separate insurance policy. But the existence of another business, by itself, doesn’t guarantee access to its insurance.
3. Underinsured Motorist Coverage
An injured person’s own automobile insurance may provide another possible source of recovery.
Washington’s underinsured motorist coverage, commonly called UIM, can help when the applicable liability insurance is insufficient to compensate a covered person for legally recoverable damages.
Under RCW 48.22.030, Washington automobile policies generally must include an offer of underinsured motorist coverage, subject to statutory exceptions and the insured’s ability to reject coverage in writing.
Whether UIM benefits are available after a commercial truck accident depends on the policy, the circumstances of the crash, applicable offsets, and the coverage limits.
It isn’t automatic additional compensation, but it’s an important possibility to investigate.
4. The Assets of a Legally Responsible Defendant
Insurance coverage and legal responsibility are different things.
A trucking company or another defendant may remain legally responsible for damages beyond the amount its insurance company agrees to pay.
However, obtaining a judgment and collecting that judgment are not the same.
The company’s assets, financial condition, corporate structure, and applicable collection laws can affect whether additional recovery is realistically possible.
This is another reason why identifying the correct defendants and understanding their financial and insurance arrangements matters before accepting a final settlement.
Can a Freight Broker Be Responsible for a Truck Accident?
Sometimes. And this is an area of trucking litigation that deserves particular attention.
A freight broker typically arranges transportation between a shipper and a motor carrier. The broker may not own the truck, employ the driver, or directly operate the vehicle.
Nevertheless, the process used to select a trucking company may become relevant when the carrier has a history of serious safety problems.
For example, an investigation might examine whether a broker had access to significant safety concerns before selecting the carrier and whether the selection process contributed to the collision.
The 2026 Supreme Court Decision on Freight Broker Liability
On May 14, 2026, the U.S. Supreme Court issued an important decision in Montgomery v. Caribe Transport II, LLC.
The case concerned whether federal transportation law prevented a seriously injured truck driver from pursuing a state-law negligent carrier-selection claim against a freight broker.
The Court held that the negligent-hiring claim at issue was not preempted by the Federal Aviation Administration Authorization Act because it fell within the law’s motor-vehicle safety exception.
That ruling removed a significant federal preemption obstacle for claims of that type.
It didn’t establish that freight brokers are automatically responsible whenever a carrier causes an accident.
An injured person must still establish the elements of a valid claim under applicable law, including negligence, causation, and damages.
You can read more about the legal issues in Defiance Injury Law’s article on trucking company negligence and freight broker liability.
What About the MCS-90 Insurance Endorsement?
Certain federally regulated motor carriers must maintain an MCS-90 endorsement as part of their financial responsibility arrangements.
The endorsement is designed to help protect members of the public by providing a financial responsibility mechanism for qualifying judgments against covered motor carriers.
However, it isn’t simply another insurance policy that automatically increases the amount available after a crash.
Whether the endorsement applies depends on its terms, the carrier, and the circumstances. It generally operates within specified financial responsibility limits and is subject to important legal conditions.
The distinction is important when an insurer disputes coverage. The endorsement may warrant investigation, but it shouldn’t be mistaken for guaranteed compensation above the trucking company’s insurance limits.
Why the Full Value of a Truck Accident Claim Matters
Before deciding whether an insurance policy is sufficient, the damages must be evaluated carefully.
A settlement that covers today’s medical bills may be inadequate for someone who will need treatment for the rest of their life.
In Washington, a serious truck accident claim may include compensation for medical expenses, future treatment, lost wages, reduced earning capacity, pain and suffering, and other legally recoverable losses.
For someone with a traumatic brain injury or spinal cord injury, the evaluation may require medical specialists, vocational experts, economists, and life care planners to understand the likely long-term consequences.
The investigation must also account for liability, available evidence, and any comparative fault.
Under RCW 4.22.005, a claimant’s share of fault generally reduces compensatory damages proportionately rather than automatically preventing recovery.
A high estimate of future losses doesn’t guarantee an equivalent settlement or verdict. But without understanding the full extent of the damages, it’s difficult to determine whether the available insurance is enough.
What Should You Do If the Insurance Company Says the Policy Limit Is All That's Available?
If you’ve been seriously injured in a Washington truck accident and an insurer tells you its policy limit is the maximum available, don’t assume that statement resolves the entire case.
There are several important steps to consider.
Ask whether additional coverage exists. The primary policy may not be the only potentially applicable policy. Excess insurance and coverage issued to other legally responsible parties may warrant investigation.
Preserve evidence of the collision. Electronic driving logs, vehicle data, dispatch records, maintenance documents, freight contracts, and communications can help establish what happened and whether other businesses contributed.
Document the long-term consequences of your injuries. Medical records, treatment recommendations, employment information, and future care assessments can be important when evaluating damages.
Have the settlement and release reviewed before signing. A settlement may require releasing the trucking company and potentially other parties. The language can affect your ability to pursue additional claims.
Also, don’t assume that an insurance investigation suspends the deadline to file a lawsuit.
Washington generally provides a three-year limitations period for personal injury actions under RCW 4.16.080, although exceptions and different deadlines may apply.
When Trucking Insurance Isn't Enough, the Investigation Matters
A serious truck accident can leave families facing financial obligations that continue long after the collision.
The amount of insurance initially identified may be important, but it doesn’t always tell the complete story.
The investigation may need to reach beyond the driver, beyond the motor carrier, and beyond the primary insurance policy.
That means examining who selected the trucking company, who maintained the equipment, who controlled the shipment, what insurance policies exist, and whether the evidence supports additional claims.
At Defiance Injury Law, our attorneys investigate serious commercial trucking accidents involving potentially responsible companies, complex liability questions, and catastrophic injuries throughout Seattle and Washington.
If you or a loved one has been seriously injured in a commercial truck accident, contact Defiance Injury Law to discuss your legal options.
Frequently Asked Questions About Truck Accident Insurance Limits
Can I sue a trucking company for more than its insurance policy limits?
Yes, a claim against a legally responsible trucking company may exceed its insurance limits. However, the insurer’s payment obligation generally depends on the applicable policy and law. Recovering additional damages may require other coverage or pursuing collection from responsible defendants.
Is $1 million the maximum compensation for a truck accident?
No. There is no universal $1 million ceiling on truck accident compensation. The damages, insurance coverage, liability, and available sources of recovery depend on the individual case. Some claims may involve multiple policies or defendants, while others have limited collectible resources.
Can I pursue compensation from both the driver and the trucking company?
Potentially. Depending on the driver’s employment relationship, the company’s conduct, and applicable law, both may face legal responsibility. That doesn’t necessarily mean each has separate insurance or that damages can be recovered twice.
Can my own insurance help if the trucking company's coverage isn't enough?
Possibly. Underinsured motorist coverage may provide benefits if you’re covered and the applicable requirements are met. Personal injury protection or health insurance may also help with certain immediate expenses, subject to coverage terms and possible reimbursement obligations.
Does the trucking company's policy limit determine what my case is worth?
No. A claim’s legally supportable value is based on the damages and relevant legal factors, not simply the insurance limit. However, the insurance and financial resources available can substantially affect how much compensation can ultimately be collected.
Should I accept a policy-limit settlement offer?
Not before understanding the available coverage, the value of the claim, and the consequences of the proposed release. A policy-limit settlement may be appropriate in some circumstances, but signing away legal rights before evaluating other potentially responsible parties or insurance policies can have lasting consequences.
Legal Disclaimer
This article provides general legal information, not legal advice. Every case depends on its specific facts, applicable law, and available evidence. Past results do not guarantee a similar outcome.